Cash Advance Now - Bear Loan

- 391.00 Reviews
- 4.7
- Downloads
- 50,000+
 Analysis by Appgk
I tend to think about borrowing apps in the context of a real household, not as a shortcut for everyday spending. A surprise bill can land when one person is out and another is managing groceries, transport, or a shared budget. In that moment, Cash Advance Now - Bear Loan may be worth considering as a finance app focused on cash-advance options. My main advice is to treat it as a starting point for evaluating a possible loan, not as money you can count on before you understand the terms and decide that repayment fits.
A quick household check before opening a loan app
When I look at a cash-advance option for a household, I separate the immediate problem from the proposed solution. A bill due tomorrow is a timing problem; borrowing is only one possible response. Before anyone reaches for a phone, I would ask what happens if the bill is paid late, whether the provider offers another arrangement, and whether a smaller payment or temporary spending change would bridge the gap without creating a second obligation.
That small pause is useful because the person browsing may not be the person who will feel the repayment most. If a partner or housemate is covering another essential expense, a loan can shift pressure rather than solve it. I would make the decision with a clear picture of the whole month, not just the balance in the account today.
When a household expense catches you off guard
Imagine a household dealing with an unexpected expense just before payday. One person finds the app, while another will ultimately share the impact of the repayment. That is a reasonable setting in which to look into a cash advance, but it is also where haste can create friction. I would first work out how much is genuinely needed, when the household expects funds to come in, and which existing expense could be adjusted instead.
The app’s focus is clear: it is for people exploring cash-advance options connected with an online loan. That makes it different from a budgeting app, a bank account, or a general financial planner. I would not open it expecting help tracking household spending or coordinating bills. Its potential role is narrower: helping a user investigate a short-term borrowing option when other practical choices have been considered.
That distinction matters in a shared home. A person may be the one using the phone, but a loan repayment can affect everyone’s plans. Before proceeding, I would discuss the decision with anyone who depends on the same household budget. A useful rule is to agree on the amount and repayment plan first, then use the app to assess whether borrowing is suitable. That avoids treating a displayed option as an automatic answer to a shared problem.
Keep the decision tied to a specific need
I would use a cash-advance app only for a defined gap, such as a necessary bill with a clear due date, and only after checking whether the expense can be delayed, reduced, or covered another way. Borrowing for routine extras is harder to justify because it can turn a temporary shortfall into another payment competing with next month’s essentials.
News Picks to Read Next
View All News


A practical check is to write down the amount needed, the next expected income date, and the household obligations that must be paid before then. If a repayment would force a choice between the loan and food, utilities, rent, or another essential, I would not proceed. The convenience of starting an online application does not make the underlying budget work.
Use a personal account boundary on a shared phone
Households often share devices for convenience, but financial decisions need clear ownership. I would keep the app and any application activity tied to the person who is actually considering the loan, rather than letting another household member enter details on their behalf. That reduces confusion about whose information is being used and who is responsible for reviewing the decision.
Best Parts of Cash Advance Now - Bear Loan
Things to Keep in Mind About Cash Advance Now - Bear Loan
If a phone is passed around, I would avoid leaving an active financial session open and would not save sensitive details where another person can casually access them. These are sensible device habits, not a claim that the app provides a particular privacy setting. Before entering personal or financial information, read the on-screen explanations carefully and make sure you understand what is being requested and why.
This is especially important when someone else is helping with the household budget. They can sit beside the applicant and help compare the choice with upcoming bills, but the applicant should remain in control of their own account and decisions. I would not share credentials simply to make coordination easier. A conversation and a written budget are safer ways to collaborate than handing over access.
Coordinate the repayment, not just the application
One useful workflow is to agree on a repayment plan before opening the application. Note which income will cover it, what other payments fall in the same period, and what the household would do if that income arrives later than expected. This is a non-obvious but important step: people often focus on whether cash might be available now and leave the harder question—how the repayment fits later—for another day.
Once a possible offer appears, I would compare its full repayment obligation with the amount received and the timing of the payment. I would read every term on screen rather than relying on the phrase “cash advance” to imply that borrowing is low-cost or risk-free. If the cost, schedule, or consequences of missing a payment are unclear, pause and seek clarification before accepting anything.
For shared expenses, decide in advance how the household will record the borrowing. A simple note in a shared budget can prevent one person from counting the same money twice or forgetting that a future pay period is already committed. That is useful whether the applicant is paying a household bill or covering a personal expense that affects joint plans. The app should not be treated as the household’s coordination system; people still need to communicate directly.
What the app’s standing tells me—and what it doesn’t
Bear Loan is free to install, has an average rating of 4.7 from around 4.3 thousand ratings, and has passed 10 thousand installs. Those figures suggest that many people have engaged with it, but popularity is not a substitute for checking whether a loan suits your circumstances. I would use the rating as a little context, not as evidence that an offer will be affordable or appropriate for every user.
Screenshots
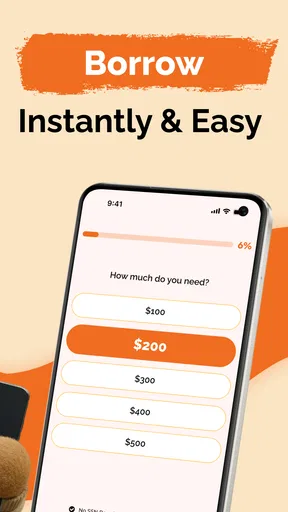
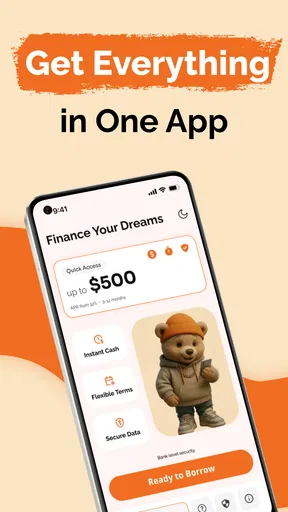
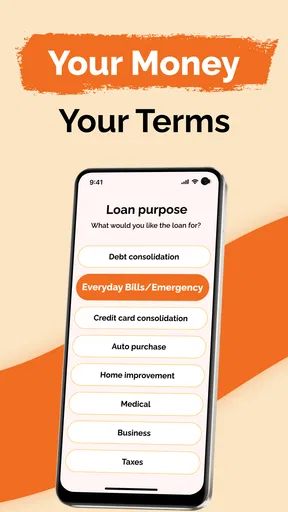
The app is developed by EPUTSTG QUALITY, and its current version is 2.2.3. It is listed for Android 7.0 and later, so someone using an older device should check compatibility before planning around it. Its price is free, but that describes access to the app, not the cost of any borrowing a user may consider. Keeping those two costs separate is essential when comparing financial options.
Compared with a bank or credit union, a cash-advance app may appeal to someone seeking an online route to explore short-term borrowing. Compared with asking a biller about a payment arrangement, adjusting a budget, or using savings, however, borrowing adds a repayment obligation rather than removing the expense. I would compare those alternatives first. A direct conversation with a service provider can sometimes solve a timing problem without taking on a new loan, while savings may be preferable when using them does not leave the household exposed to another emergency.
Age, trust, and the person responsible
The app carries an Everyone content rating, but that is a content classification, not a signal that taking out a loan is suitable for every age or situation. Financial borrowing should be considered by an adult who understands the terms and is legally able to enter the relevant agreement. I would not let a child or teenager use a parent’s device to explore or submit a financial application, even if the app itself is classified for general audiences.
In a household, trust also means being clear about who is applying and who will owe the money. A relative may help review a budget or talk through alternatives, but that should not blur responsibility for an application. If the person expected to repay cannot explain the amount, timing, and consequences in their own words, I would wait rather than move ahead.
I would also resist pressure from anyone who says an application must be completed immediately. A short pause to review terms and consult the household is a sensible safeguard. If the opportunity only seems workable when nobody asks questions, that is a reason to stop and reassess, not a reason to hurry.
Questions I would settle before relying on a possible offer
A practical question is whether using the app means money will definitely be available. I would not plan a payment around that assumption: exploring an online loan option is not the same as having a confirmed advance. Until an offer is clear and accepted on terms the applicant understands, I would keep a fallback plan for the bill rather than promise a household member that the funds are on the way.
I would also ask whether the amount being considered is the amount the household actually needs, and whether the repayment date lines up with income after other commitments. If a quoted repayment looks manageable only because groceries, transport, or utilities have been left out of the calculation, it is not a realistic plan. Writing those expenses down first is a simple way to catch that mismatch.
For someone comparing options, the key is to compare like with like: total repayment, timing, and what happens if payment is late, not just how quickly an application can be started. A bank, credit union, biller arrangement, or savings may be preferable depending on the person’s circumstances. I would choose the option that leaves the household with the clearest, most sustainable path through the next pay period, rather than the one that merely feels quickest on a phone.
Who I’d recommend it to, and who should look elsewhere
I can see this app being useful to an adult who wants to investigate cash-advance options online, has a specific short-term need, and is prepared to scrutinize repayment terms before making a decision. It may also suit someone who prefers to begin researching on a phone rather than visit a physical institution, provided they keep expectations realistic and compare other routes.
I would skip it if you need a budgeting tool, want an app that coordinates bills among several household members, or are looking for a guaranteed source of cash. I would also avoid borrowing if repayment depends on taking out another loan, if the household cannot absorb the scheduled payment, or if the terms do not make sense after careful reading. In those cases, contacting the biller, reviewing expenses, or seeking independent financial guidance is a better next step.
My overall view is cautious but practical. Cash Advance Now - Bear Loan has a focused purpose and a substantial base of ratings, yet the useful question is not whether a cash advance is easy to investigate; it is whether borrowing improves the household’s position after repayment is counted. For a shared-device household, keep the applicant’s account and information under that person’s control, discuss any shared budget impact openly, and do not mistake the free app for free credit. Used as one place to explore an option—not as a substitute for comparison or a repayment plan—it may be worth a look.
Cash Advance Now - Bear Loan FAQ
What is Cash Advance Now - Bear Loan?
Cash Advance Now - Bear Loan appears to be a financial app intended to connect users with cash-advance or loan options. The app’s name alone does not establish who provides the funds, whether it is a direct lender, or what products are available in your location. Before applying, review the developer’s details, eligibility rules, and the complete terms shown in the app, and confirm that the service is available where you live.
How do I apply, and what information might I need to provide?
The application process and required documents can vary by provider and location. You may be asked for identifying and contact details, employment or income information, and bank-account information so an offer can be assessed or funds can be delivered. Enter personal or financial data only after checking the app’s privacy policy and verifying the provider. Never share a banking password, one-time security code, or other credentials that a legitimate service should not need.
How much does a cash advance cost, and when must it be repaid?
Costs and repayment schedules depend on the specific offer, lender, and applicable local rules; the app’s title does not confirm a particular fee, interest rate, or repayment date. Before accepting anything, look for the amount you will receive, the total amount due, any interest or fees, the due date, and possible late-payment consequences. If these details are unclear or unavailable before you commit, do not proceed until the provider explains them.
Is Cash Advance Now - Bear Loan safe, and what should I check before downloading?
No app can be judged safe from its name alone. Download it only from the official Google Play or Apple App Store listing, and check the listed developer, recent reviews, update history, privacy disclosures, and requested permissions. Be cautious if the app asks for access unrelated to its stated service, promises guaranteed approval, or pressures you to pay an upfront fee. Confirm that its privacy and support information are clear before sharing sensitive data.
Who can use the app, and what if I need help or want to cancel?
Eligibility may depend on your age, residence, income, bank account, and the rules of the lender or service provider; approval is not guaranteed. Check the current requirements and support or complaint channels in the official listing and within the app. If you have accepted an offer, cancellation and repayment rules may be set by the provider rather than the app itself. Read the agreement carefully and contact the provider promptly about disputes or account closure.